Case study · THE ONE, Southbank
Level 38 · Sold October 2026The rent carries the mortgage.
A Singapore family was ready to pay cash for a A$1.85M river-view residence. Here is the structure that convinced them to keep over A$1 million of their capital free instead, and every number behind it.
Purchase price
A$1.851M
Borrowed
55%
Cash after all costs
+A$430
per month, modelled
Loan repaid in 5 yrs
A$65K
built from the rent
The idea in one minute
Cash buys the apartment. A loan, carried by the rent, buys the apartment and keeps your capital.
01
The brief
Positive cash flow, no stress. The family planned to buy outright for their son, who is studying in Australia.
02
The question
Why lock up over A$2 million in one apartment, when a corporate tenant can pay for a loan on half of it?
03
The answer
Borrow 55%. The rent covers the running costs and the full mortgage repayment, and pays down the loan every month.
The residence
38.08, THE ONE
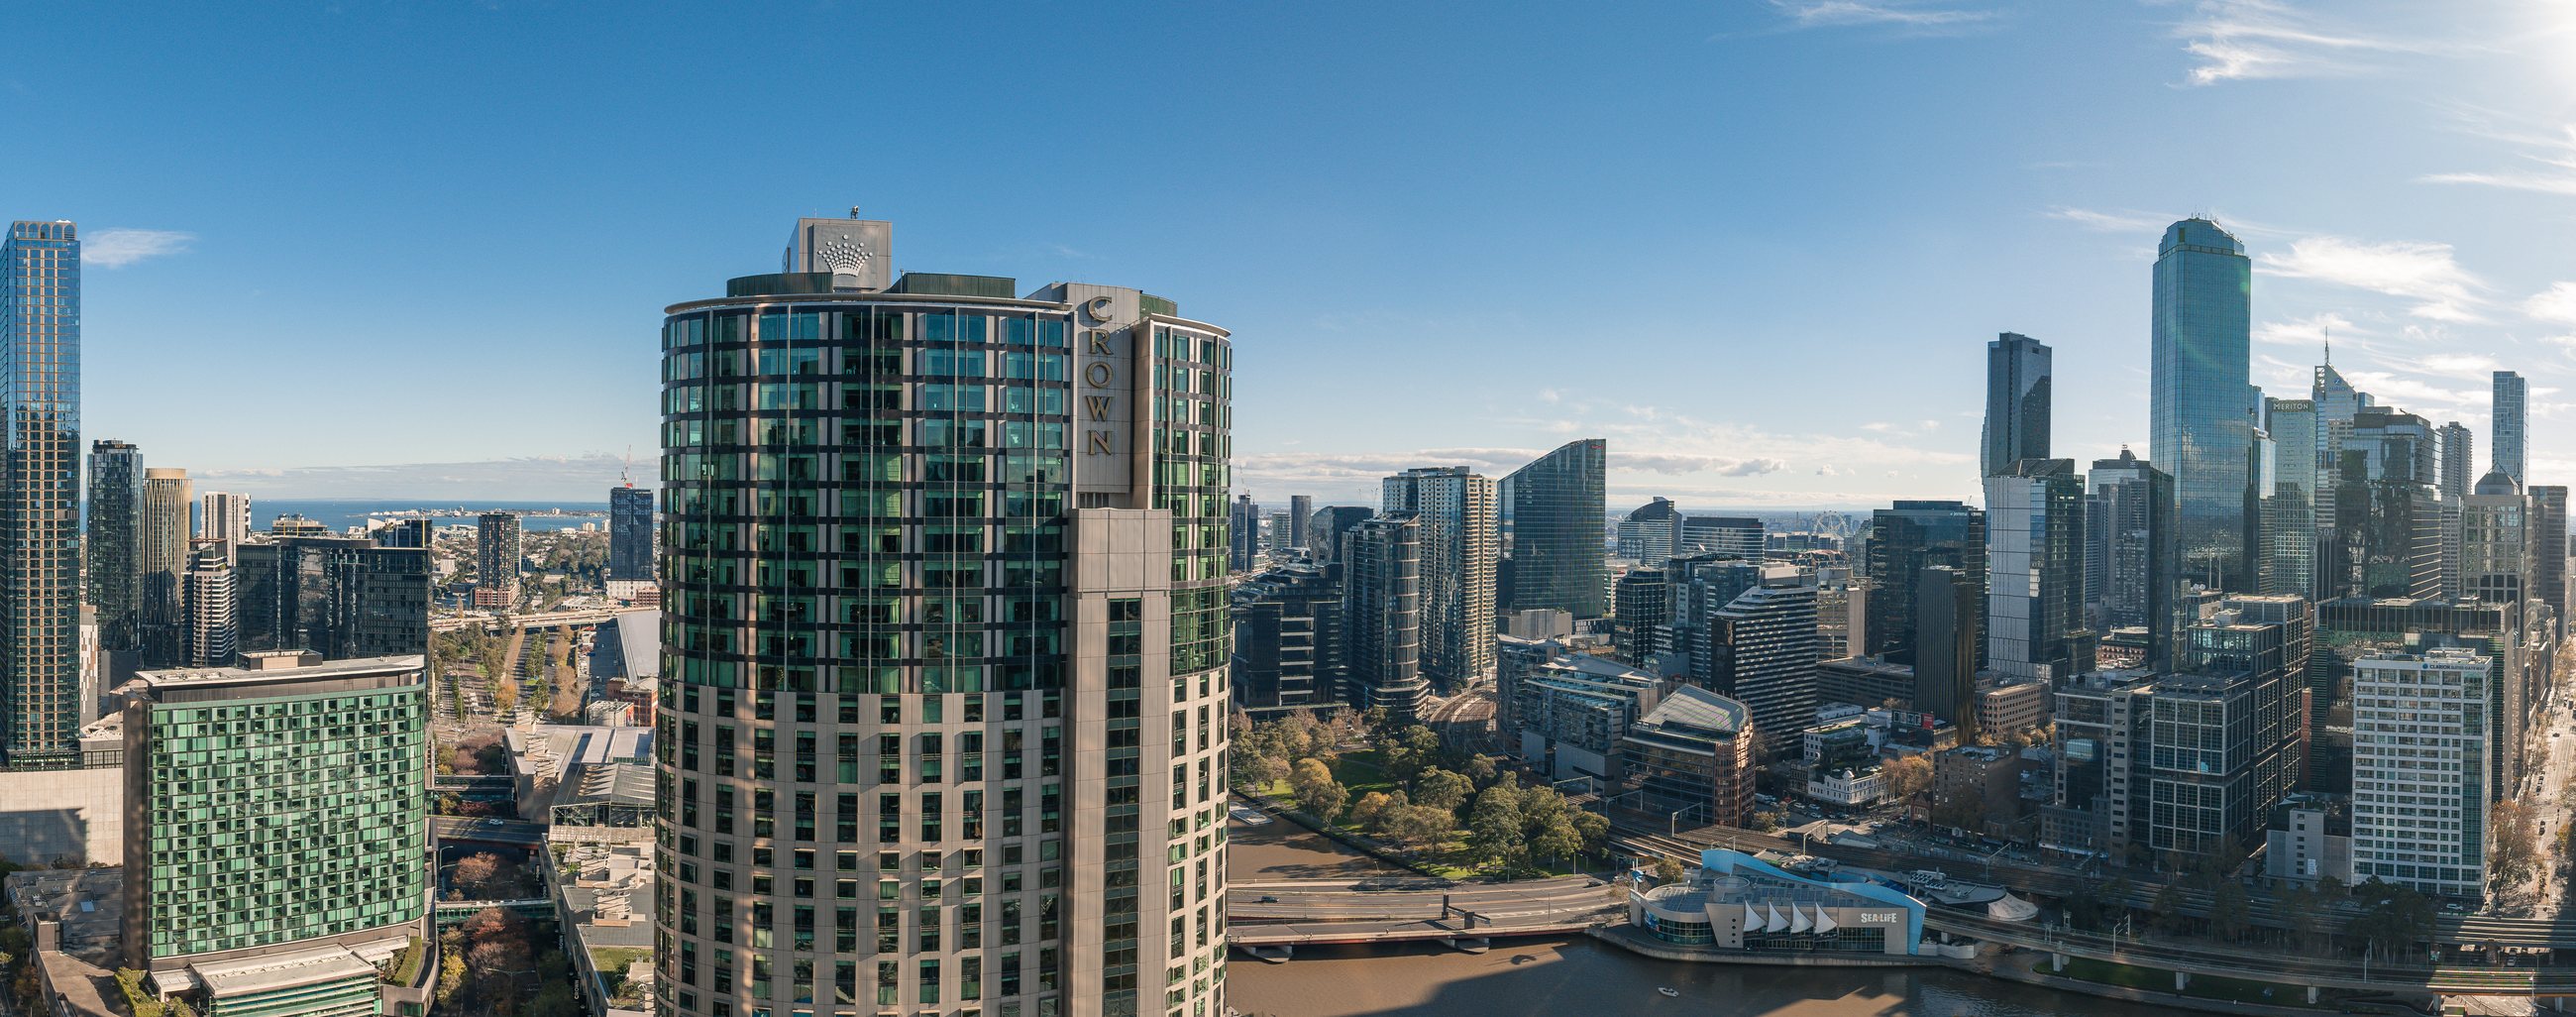
A 92 m² two-bedroom corner residence on the 38th floor of THE ONE at 1 Queens Bridge, Southbank, looking west over Crown, the Yarra and the CBD skyline. Corporate tenants pay a premium for this: two bedrooms with their own bathrooms, a ten-minute walk to the CBD, and a hotel tower address.
Level
38
Bedrooms
2
Bathrooms
2
Car park
1
Internal
92 m²
Aspect
West · Crown & river
Price A$1,851,000 · 10% deposit today, the balance at completion (expected 2029–30).
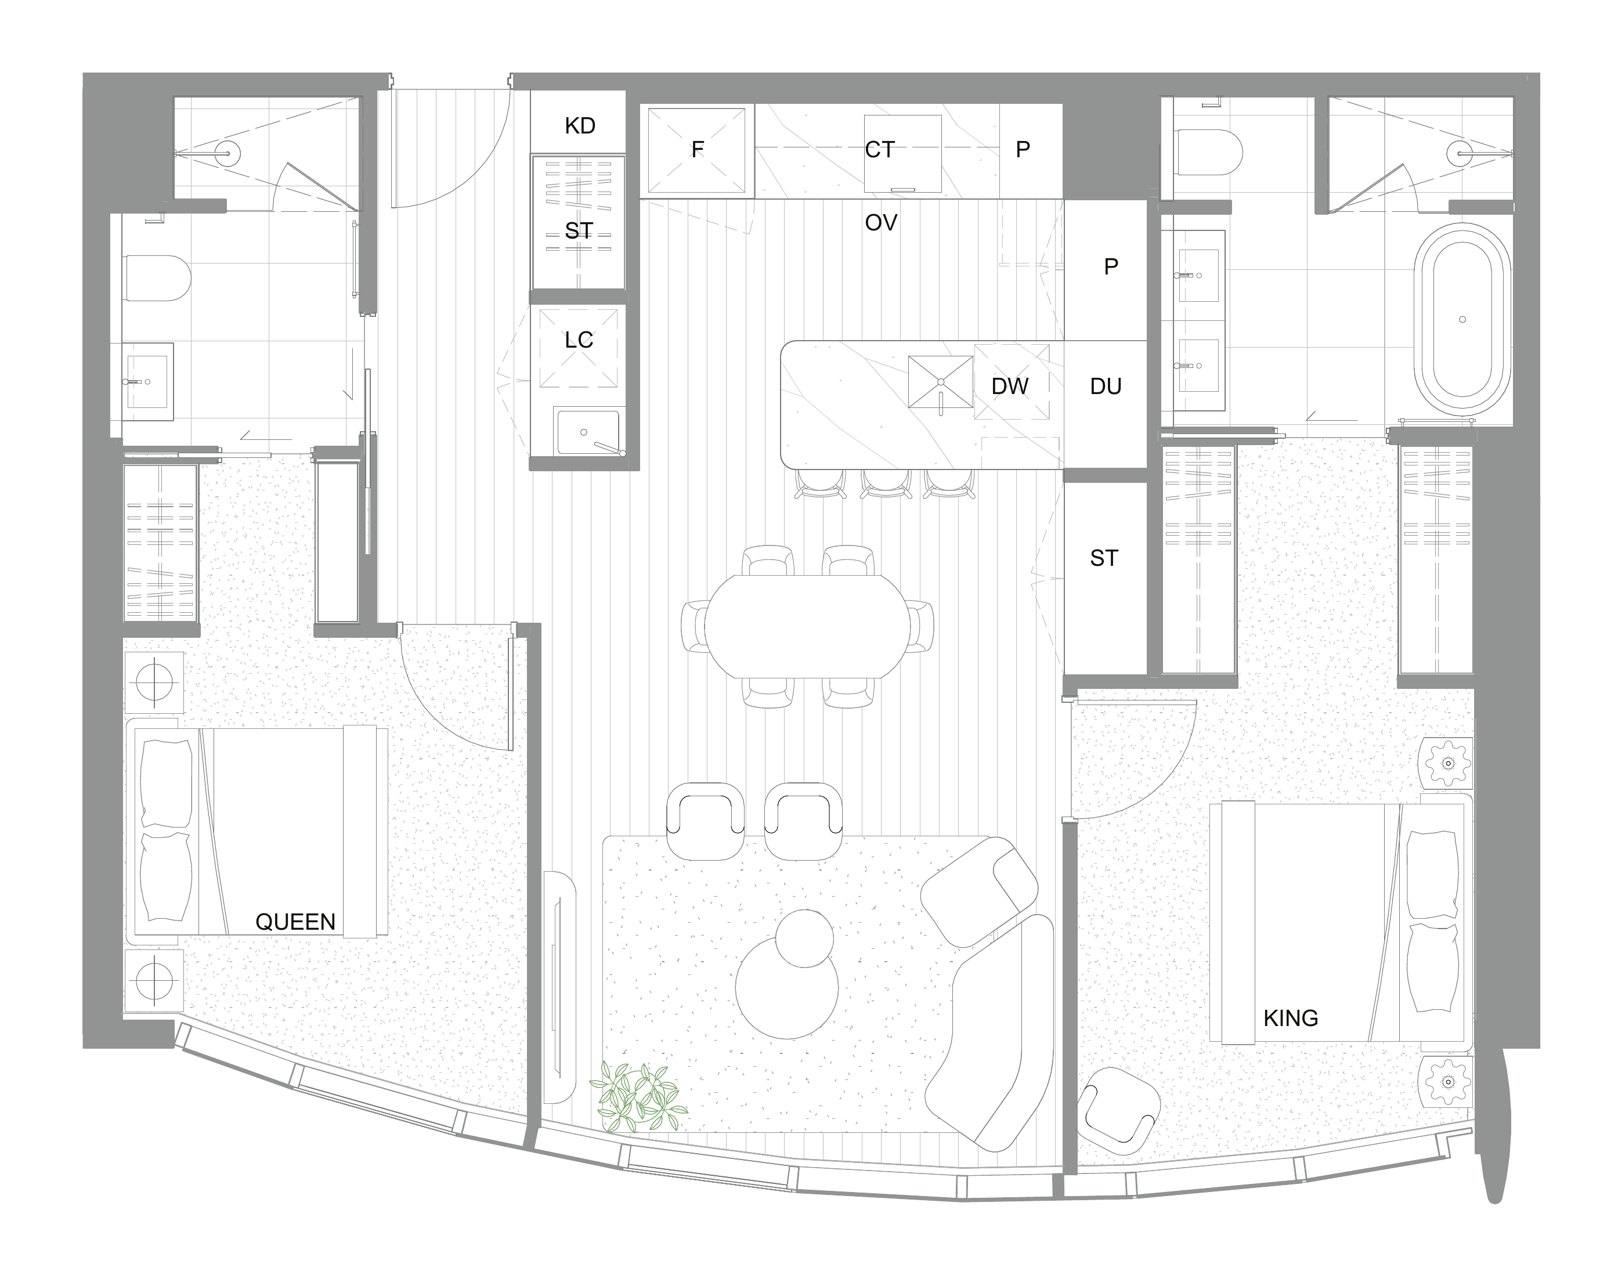
Type C03.1 floor plan, as supplied by the developer. Furniture is indicative.
Try it yourself
Choose how much to borrow.
Every number on this page updates as you move these. They start on the family's choice: 55% borrowed, 44 weeks of corporate leasing a year, 6.50% interest.
Loan, as a share of the price
Your cash in, all costs
A$1,064,577
A$1,015,550 less than paying cash
Mortgage, principal + interest
A$6,435/mo
Loan A$1,018,050 over 30 yrs
Rent after running costs
A$6,865/mo
A$82,375 a year
Left in your pocket
+A$430/mo
after the full mortgage repayment
At these settings the tenant pays every running cost and the whole mortgage repayment, with A$430 a month to spare. Meanwhile the loan shrinks by about A$65,043 over five years.
The ownership engine
Where a year of rent goes.
A corporate tenant pays A$2,500 a week. After the building, the council, the state and the manager are paid, what's left goes to the bank, and part of every repayment is your own loan getting smaller.
A$2,500 a week × 44 paid weeks
Management, owners corp, rates, land tax, absentee surcharge
Principal and interest, 30 years
Five years after completion
The tenant builds your equity.
Over the first five years of renting, this is what the rent does — before any change in the apartment's value, which this page deliberately leaves out.
Rent after running costs
A$411,875
Interest paid to the bank
A$321,043
Your loan paid down
A$65,043
Cash kept
A$25,789
Working for you over five years: A$90,832
loan repaid + cash kept
The honest trade-off
Why not simply borrow less?
You could. A 50% loan leaves more cash each month. The rent, after costs, returns 4.45% of the price a year, and money borrowed at 6.50% costs more than that, so each extra dollar borrowed slightly reduces the monthly surplus.
The family chose 55% anyway, for liquidity: A$92,550 stays in their hands for other plans, and the rent still covers everything. It is a choice between two good objectives, not a right and a wrong answer.
Choose 50% when…
a bigger monthly safety margin matters more than keeping the last A$92,550 of capital free.
Choose 55% when…
capital for other opportunities comes first, and a modest monthly buffer is enough.
What if the apartment sits empty longer?
Monthly cash left over at 55% borrowed, by paid weeks a year
No surprises
Every dollar you put in.
Foreign buyers pay more to get in than locals do, and we show it upfront. The biggest item is Victoria's 8% foreign purchaser duty. Only A$185,100 (the 10% deposit) is needed at signing; the rest comes at completion, expected 2029–30.
Total cash in at 55% loan
A$1,064,577
Your share of the price (45%)
Includes the 10% deposit paid at signing
A$832,950
Off-the-plan general duty
Concessional estimate from the developer
A$11,247
Foreign purchaser additional duty (8%)
Charged on the full price
A$148,080
FIRB application allowance
If required
A$31,300
Legal & settlement
Allowance
A$3,500
Loan set-up
Only if borrowing
A$2,500
Furnishing & styling
Ready for corporate leasing
A$35,000
Tax, explained simply
Depreciation is not rent in your pocket.
Two different sums matter. Cash flow is rent minus costs minus the full mortgage repayment. Taxable income is rent minus costs minus only the interest, minus depreciation on the new building and fittings. Repaying the loan itself is not deductible.
In this example the first year shows a tax loss of A$13,463. With no other Australian income, that loss is carried forward, not refunded, and the rent may attract no Australian income tax that year. We never add depreciation to the cash figures above.
What the family asked us
The questions every overseas buyer asks.
The family started with parent and son together, to keep options open. For this contract the solicitor confirmed the parent can be removed before settlement without a further FIRB fee or extra Victorian duty. Confirm this for your own contract.
Yes, but a trust needs its own FIRB application and adds cost. For most families it is simpler to decide names now and revisit estate planning closer to settlement.
Not automatically. His home is where he lives; this is an investment property with its own rent, expenses and depreciation. A mortgage-free first property can even help an Australian loan application later.
Both work. Equity from a Singapore property avoids the need for an Australian income at settlement. An Australian loan keeps the debt in the same currency as the rent, and its interest is usually deductible against that rent. How the money reaches the buyer (a gift or a properly documented loan) changes the tax result, so compare the after-tax cost closer to settlement.
No. Only the names on the contract and the 10% deposit are needed today. Finance is decided near completion, when rates and circumstances are known, and paying cash remains an option.
Your turn
Want this analysis on your apartment?
We'll model any residence still available at THE ONE the same way: real rent, real duties, your loan options, your tax position. No obligation, and we'll show you the weak spots as well as the strong ones.
See the residences hand-picked at THE ONE